
 KOR
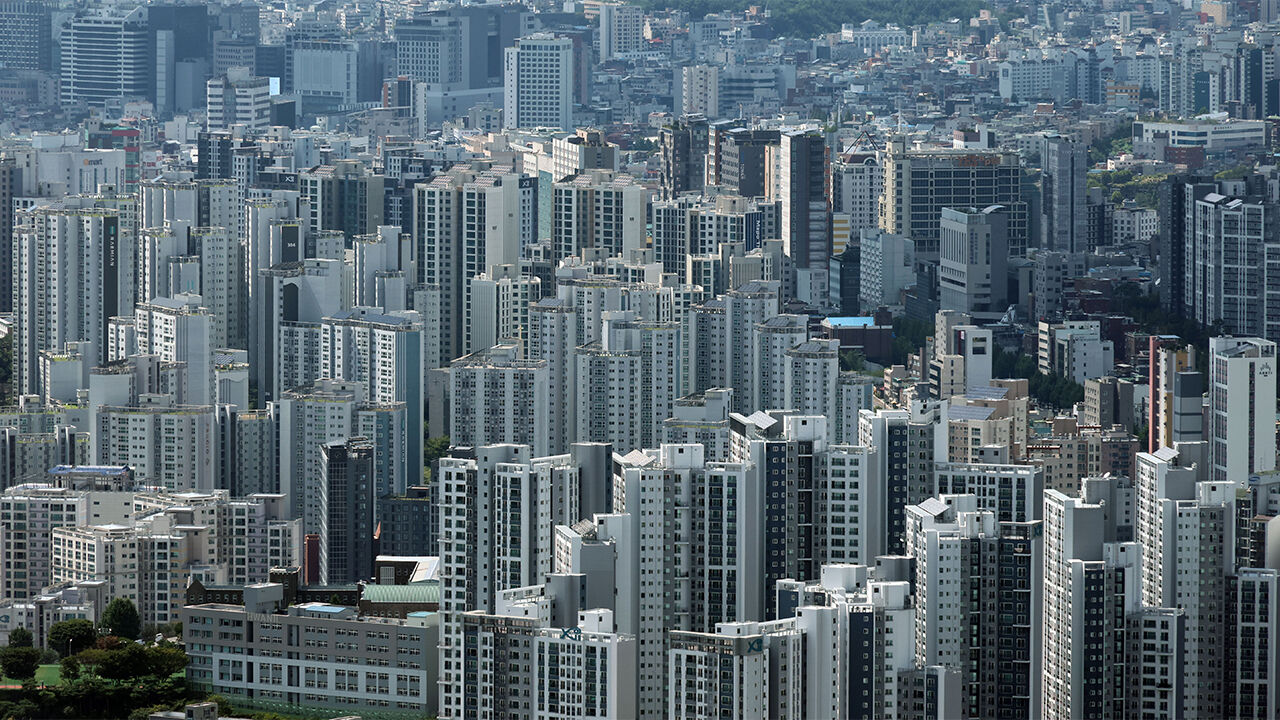
▲ Apartment complex area in Seoul
The National Assembly's Strategy and Finance Committee has raised a review opinion that increasing the comprehensive real estate holding tax rate could drive up housing rents and potentially shift the tax burden onto tenants.
Heated debate is expected as the National Assembly is set to begin full-scale deliberations on government-proposed tax law revisions, including the amendment to the Comprehensive Real Estate Holding Tax Act, in the near future.
According to tax authorities and political circles on October 25, the Strategy and Finance Committee recently stated this in a review report on tax-related bills drafted under the name of Chief Professional Examiner Lee Jung-eun regarding the plan to raise the housing comprehensive real estate holding tax rate contained in the bill.
In the report, the committee observed, "Views can be raised that a high holding tax burden on multiple homeowners could lead to increased costs for landlords and potentially shift the tax burden onto tenants in the form of higher rents. In such cases, contrary to the policy objectives, it may distort the lease market, such as increasing the housing cost burden for tenants."
It also introduced concerns that raising the tax rate could aggravate the tax burden on single-home owners, resulting in "restricting economic freedom and the freedom of movement of residence, regardless of the policy objective of alleviating ownership concentration."
The bill to revise the Comprehensive Real Estate Holding Tax Act includes a plan to unify tax rates based on housing value while raising the rate for brackets exceeding 600 million won in the tax base compared to the current level.
The tax rate for the bracket exceeding 600 million won up to 1.2 billion won, currently subject to 1.0%, will be raised to 1.3% after 2028.
For the four brackets exceeding 1.2 billion won, the tax rates for holders of two or fewer homes will increase by 0.7 to 2.3 percentage points (p).
Noting that the comprehensive real estate holding tax is levied based on asset prices rather than realized income, the committee paid attention to the possibility that it "can aggravate tax burdens detached from taxpayers' short-term income and cash flow," potentially triggering tax resistance or leading to policy effects different from expectations.
Regarding this, the committee pointed out, "While the increase in holding costs resulting from higher comprehensive real estate holding tax rates should theoretically act as a factor lowering housing prices, various factors beyond the tax burden—such as interest rates, income, housing supply, and financial conditions—affect housing price determination. Therefore, the policy impact of the tax rate hike could be diluted," adding that "the policy effects may not sufficiently appear at the expected time."
The committee projected that regarding setting the basic deduction amount for the comprehensive real estate holding tax differentially based on residency status, "opinions could emerge to consider the possibility of tax burdens being shifted onto tenants—such as a decrease in supply and a rise in rents in the Seoul metropolitan area lease market—or the possibility of intensifying the concentration in the metropolitan area."
The bill stipulates the basic deduction amount for multiple homeowners as '500 million won × (residency housing value ÷ total housing value) + 400 million won.'
This formula is intended to act as an element that entices multiple homeowners to reside in relatively expensive housing in the metropolitan area in order to increase their basic deduction amount.
The committee added, "Accordingly, the concentration phenomenon in the metropolitan area may intensify, and the supply in the metropolitan area lease market is likely to shrink further. There is a possibility that rents could rise due to the decrease in supply, and the tax burden could be shifted onto tenants as the increased tax burden is reflected in rents."
Regarding the plan to raise the lower limit of the fair market value ratio, which affects the tax base, from 60% to 70%, it added that there is "concern that the tax burden on high-asset, low-income households facing cash flow constraints may increase excessively, overlapping with the tax rate hike."
However, the committee evaluated that following the upward adjustment of the basic deduction amount for single-home resident owners, "it will be possible to alleviate the tax burden on those with relatively small-scale housing."
In addition, it conveyed expectations shared by supporters of the revision that differentiating the basic deduction amount based on residency status would have the effect of suppressing real estate speculative demand.
The government has also proposed amendments to the Income Tax Act to convert the long-term holding special deduction (which applies a deduction of up to 80% when a single-household, single-home owner sells a house) into a long-term residency income deduction, while limiting the currently unlimited deduction amount to 1 billion won starting in 2029.
The expected effects and side effects of reforming the long-term holding special deduction were also included in the report.
While mentioning that supportive opinions on the reform could emerge from the perspective of inducing housing ownership centered on actual residency and enhancing taxation equity, the committee cited the possibility of adverse effects, stating it "may depress real estate transactions and reduce the supply of listings in the market."
The intent is to consider that starting in 2029, when the holding deduction is eliminated, non-residents concerned about increased capital gains taxes may delay sales to meet the residency period requirement, or those expecting the deduction limit to rise again in the future may postpone sales, creating a lock-in effect, which could reduce lease properties and listings.
The committee conveyed the opinion that the government reform plan "fails to protect the legitimate expectations and trust of taxpayers who have held real estate for a long time expecting the long-term holding special deduction," highlighting ways such as extending the grace period prior to the reform.
Furthermore, it suggested that when reforming the comprehensive real estate holding tax and the long-term holding special deduction to favor residents, consideration should be given to those who fail to meet the requirements due to unavoidable reasons such as work or education.
The committee also expressed opinions on tax law amendments outside of real estate.
It evaluated that expanding the maximum limit for the family business inheritance deduction from the current 60 billion won to 100 billion won could weaken the wealth redistribution function of the inheritance tax and exacerbate tax regressivity by granting benefits to heirs inheriting large businesses.
It diagnosed that if the tax support child birth/adoption deduction is transferred to future response fund projects and converted into financial support, securing revenue could depend on tax revenue conditions, making it difficult to judge whether it will be operated stably in the future.
The committee analyzed that the Comprehensive Investment Account (ISA) for productive finance, whose establishment is being pursued, could concentrate benefits on subscribers with large financial capacities.
(Photo: Yonhap News)
※ Please note: This article was translated by AI and may contain errors.

 Video News
 Video News
 Video News
 Video News
 Video News