
 KOR
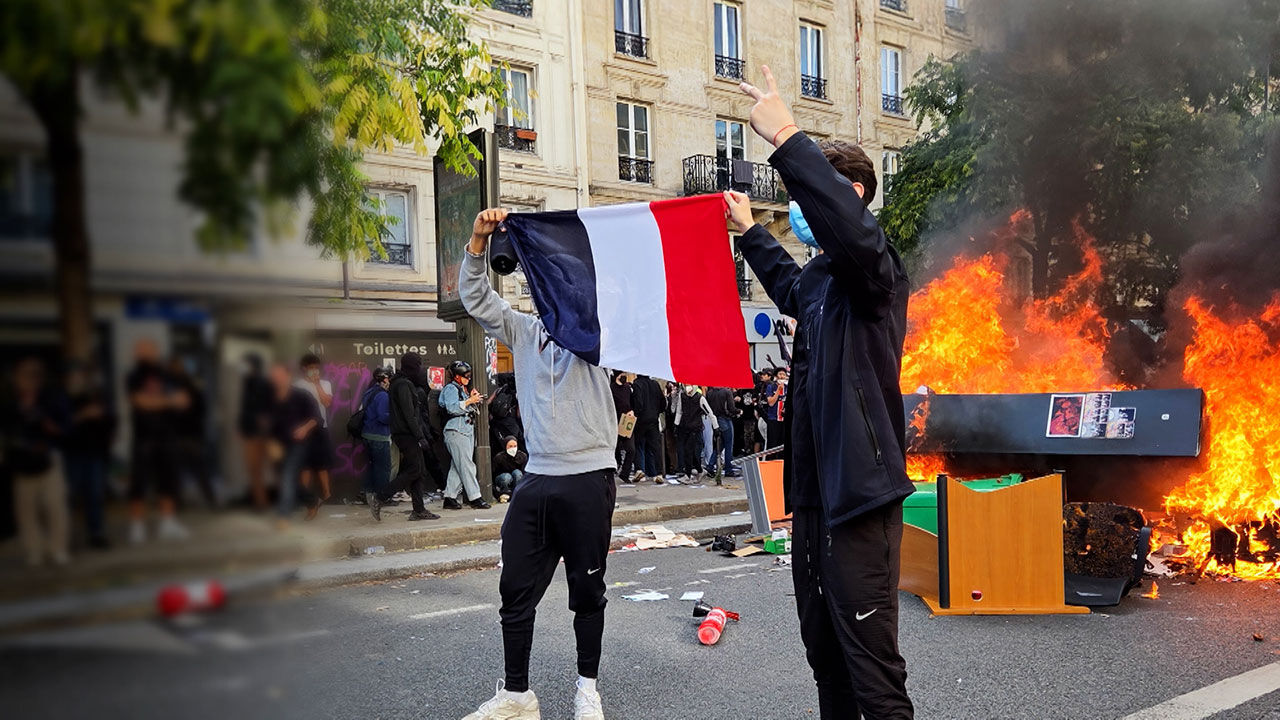
▲ Protests by French high school students
France, which has long served as a pillar of the eurozone economy alongside Germany, has plunged into a fiscal crisis due to years of excessive government spending, reducing it to the most vulnerable nation in Europe.
The fractured political landscape has failed to demonstrate any capacity to manage the crisis, instead churning out populist pledges, which has led global investors to turn their backs on the country.
The crisis originating in France also carries the potential to spill over into neighboring countries and the entire eurozone, putting pressure even on the euro.
As the French fiscal crisis intensified late last week, the yield on 10-year French government bonds approached 5%, hitting its highest level since 2002.
Current bond issuance yields are even higher than those of Greece or Italy, which were the epicenters of past fiscal crises.
France's fiscal deficit scale is second only to that of the United States among major economies.
The Wall Street Journal (WSJ) reported on the 5th (local time) that the sell-off in government bonds originating in France is spreading across Europe, reviving the nightmares of the eurozone debt crisis from a decade ago.
Investors are bracing for the situation to worsen further.
Funds borrowed during the ultra-low interest rate era are reaching maturity, but soaring interest rates have substantially increased refinancing burdens.
With maturing debt exceeding $1 trillion through 2030, France is faced with issuing approximately $380 billion in government bonds next year alone to service it.
Investors who had steadily bought French government bonds, such as Japanese asset management firms, have pulled out.
Kevin Thozet, a portfolio advisor at French asset management firm Carmignac, said, "France has been free-riding in Europe for decades and was able to get away with loose fiscal management without facing significant sanctions. That approach worked when people weren't paying attention, but now people are starting to watch the situation closely."
France's debt-servicing costs are projected to surge by 59% through 2030.
They currently make up a major share of the French government's budget and are expected to surpass defense spending by around 2030.
France's debt-to-GDP ratio is approaching 120%, carrying the risk of a "gradual strangulation" of the economy, as noted by the governor of the Bank of France.
The political establishment, which should be resolving the situation, is severely divided.
Prime ministers who attempted to stabilize the fiscal crisis through spending cuts have been ousted one after another.
Leading contenders to succeed President Emmanuel Macron are only churning out promises to expand government spending.
Far-right candidate Marine Le Pen, who is leading in opinion polls, has pledged to lower the retirement age to 60, a move that would require an additional 9 billion euros ($10.1 billion) annually if implemented.
Her rival, far-left candidate Jean-Luc Mélenchon, demands that the European Central Bank (ECB) freeze or write off the 488 billion euros in debt that the French government owes to the Bank of France.
Mélenchon argued, "Throw it into the fire."
Sylvain Maillard, a lawmaker from President Macron's centrist party, remarked, "There is always a reflex in France to demand 'magic money' from the state to foot the bills."
Here, "magic money" is a term used derogatorily by the public and politicians to refer to seemingly endless state finances.
France's fiscal crisis immediately translated into a decline in the value of the euro.
The euro-to-dollar exchange rate fell below $1.12 on the 5th, hitting a 17-month low.
It also plummeted against the British pound, Swiss franc, and Japanese yen.
As global investors dumped French bonds in favor of safe-haven German bonds, the yield spread between the two countries widened to its largest level since the 2010–2012 eurozone debt crisis.
Kit Juckes, chief FX strategist at Société Générale, analyzed, "The bond sell-off is more pronounced in assets perceived as vulnerable in any form, and as a result, the euro sell-off is also gaining momentum and spreading."
Stephen Jen, CEO of Eurizon SLJ Capital, projected, "While the euro is already somewhat undervalued, the euro-to-dollar exchange rate could fall further if the risk of a European fiscal crisis contagion is not contained."
※ Please note: This article was translated by AI and may contain errors.

 Video News
 Video News
 Video News
 Video News
 Video News