
 KOR
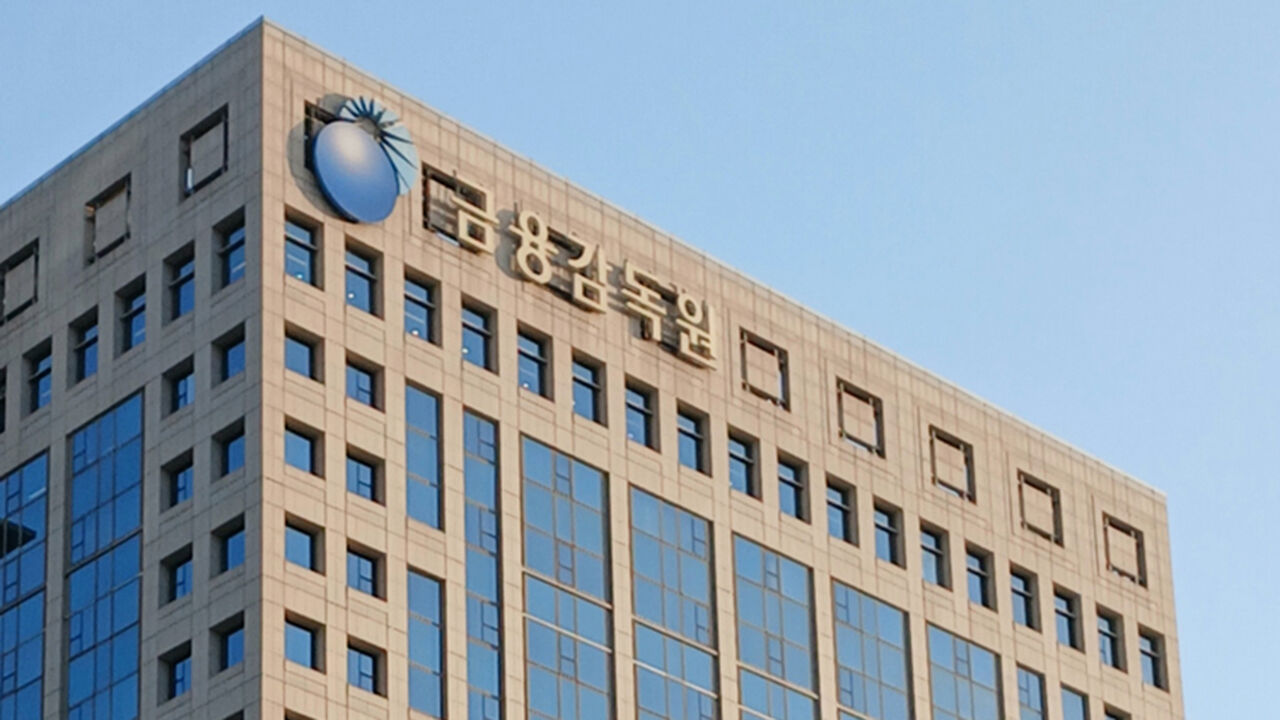
▲ Financial Supervisory Service
The Financial Supervisory Service (FSS) shared major dispute cases regarding fetal and caregiver insurance today (14th) and called for strengthened proactive consumer protection starting from the claims payment stage.
During an expanded meeting of department heads for consumer protection and claims held today, the FSS outlined recent cases of increasing disputes and its supervisory direction.
The meeting expanded attendance to include claims departments, building upon the previous consumer protection department head meetings.
Regarding fetal insurance, the FSS noted instances where contracts were canceled because pregnant women failed to disclose medical histories largely unrelated to the fetus prior to contracting, asking that excessive disadvantages not be imposed on consumers.
Fetal insurance is a product that primarily covers risks for the unborn child, obligating pregnant applicants to notify insurers of certain matters prior to subscription.
Because these policies transition into children's insurance after birth, disputes have arisen as insurers cancel entire contracts based on the pre-contract notification duty.
In one actual case, an insurer canceled the entire fetal insurance contract for a second child on the grounds that the mother failed to disclose her emergency cesarean section during the birth of her first child, and the FSS mediated the dispute so that the contract concerning the child would be maintained.
Regarding caregiver insurance, the FSS urged insurers to prevent innocent victims from suffering due to excessive demands for proof as fraudulent claims, such as fabricated family caregiving, continue to rise.
In addition, insurers were urged to review the potential for third-party-related risks company-wide starting from the insurance product design stage to prevent insurance payout leaks caused by third parties.
Operating consultative bodies that reflect the opinions of consumer protection and claims assessment departments during product development was presented as an example.
The FSS also pointed out issues where some insurers excessively conducted medical consultations, leading to delays in insurance payouts.
Mention was made of practices such as demanding additional consultations even after university hospital reviews or restricting consumer choice by limiting the choice of hospitals.
The FSS ordered that medical consultations be limited to cases where medical judgments are difficult, and that attending physicians' opinions and treatment records be thoroughly reviewed prior to making requests.
It also requested that a list of target hospitals be provided and fully explained.
Furthermore, major examples regarding claims operations related to the extracorporeal shock wave therapy dispute mediation standards established last June were presented, with a request to ensure consumers do not suffer damages.
The FSS plans to actively respond to balloon effects and insurance fraud stemming from the designation of manual therapy as a managed benefit, and cooperate on investigations into nursing hospital kickbacks.
While requesting prompt civil complaint and dispute handling from insurers, the FSS also plans to frequently share dispute handling cases through the "Key Man" system, which designates dedicated staff for disputes.
The FSS emphasized, "We will closely monitor dispute trends by company and type, check for anomalies, and conduct on-site inspections if necessary."
(Photo: Yonhap News)
※ Please note: This article was translated by AI and may contain errors.

 Video News
 Video News

 Video News
 Video News