SBS NEWS
Pre-IPO Demand Forecasting System Adopted to Secure Long-Term Institutional Investors
Published : Nov 3, 2026 4:34 PM

▲ Financial Services Commission
A "pre-demand forecasting and cornerstone investor system" will be introduced in the domestic initial public offering (IPO) market to encourage institutional investors to hold shares for medium to long terms.
The Financial Services Commission (FSC) announced that the revision to the Enforcement Decree of the Capital Markets Act containing these measures was approved during the Cabinet meeting today (3rd).
Concerns have been continuously raised that institutional investors engage in short-term trading of public offering shares in the domestic IPO market, leading to strong selling pressure right after listing and causing sharp drops in stock prices.
In response, the FSC included the "pre-demand forecasting system" in the revision to gauge demand from institutional investors before submitting the securities registration statement.
General private collective investment business entities and investment discretionary business entities must have entrusted assets of 30 billion won or more to participate in pre-demand forecasting.
While this matches the current eligibility criteria for demand forecasting, the requirement allowing a relaxation to 5 billion won after two years of registration has been excluded from the revision.
Requirements such as corporate value evaluation capabilities and internal management capabilities for undisclosed information under the Korea Financial Investment Association regulations must also be met.
After drafting a due diligence report, the lead underwriter can provide corporate information to be disclosed in the securities registration statement to institutional investors and gauge demand, such as desired purchase prices or volumes.
At this time, confidentiality agreements must be signed regarding the information provided.
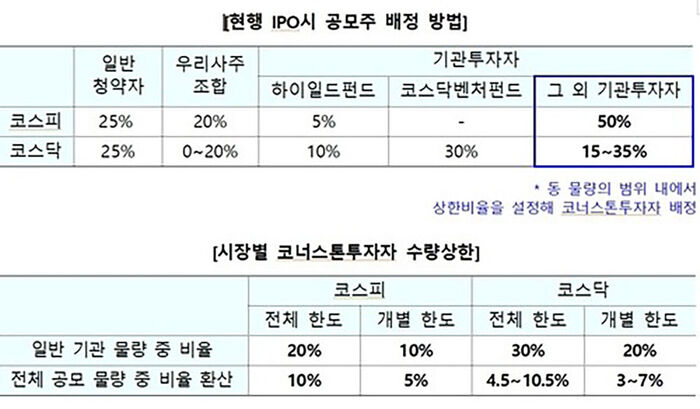
The revision also includes the "cornerstone investor system," which pre-allocates a portion of public offering shares to institutional investors who hold them long-term for six months or more.
In addition to meeting the eligibility for the "pre-demand forecasting system," participants must satisfy equity capital or asset scale requirements capable of absorbing stock price volatility risks during the lock-up period to participate as cornerstone investors.
They must possess equity capital or entrusted assets of at least 20 times the pre-subscription public offering share volume.
The FSC explained, "Since these are relative criteria, opportunities will be granted not only to large institutional investors but also to small and medium-sized institutional investors."
The lock-up periods are differentiated based on the proportion of allocated shares.
This is to prevent selling concentration that could occur if the lock-up end dates for cornerstone investors coincide on a specific day.
Of the shares allocated to cornerstone investors, 50% will have a 6-month lock-up, 30% an 8-month lock-up, and 20% a 10-month lock-up.
The upper limits on public offering shares that can be pre-allocated to cornerstone investors are set differently by market.
Among the institutional allocation ranges excluding retail investors, employee stock ownership associations, and policy funds, the limits are capped at 20% of the total limit and 10% for individual limits on the Kospi, and 30% of the total limit and 20% for individual limits on the Kosdaq.
The FSC also added elements to prevent conflicts of interest that may arise under the cornerstone investor system.
To prevent lead underwriters from pre-allocating large amounts to affiliates in highly competitive IPOs, or allocating to affiliates to boost competition rates in IPOs with risks of under-subscription, contracts with institutional investors having conflicts of interest, such as major shareholders or specially related parties, are fundamentally prohibited.
Exchanging direct or indirect benefits on the condition of cornerstone investor contracts is also banned.
The revision is scheduled to take effect from the 13th.
(Photo provided by Yonhap NewsTV, Financial Services Commission, Yonhap News)
※ Please note: This article was translated by AI and may contain errors.
Copyright Ⓒ SBS. All rights reserved. Unauthorized reproduction, redistribution, and use for AI training are prohibited.