SBS NEWS
7 Out of Top 10 Auto Parts Makers by Revenue Growth Are Chinese Companies
Published : Oct 21, 2026 11:29 AM

▲ CATL exhibition booth in China
While global top 100 auto parts makers saw modest revenue growth last year, 7 out of the top 10 companies with the highest revenue growth rates turned out to be Chinese firms.
China's parts ecosystem appears to be growing rapidly alongside its finished car manufacturers.
According to the "Analysis of the World's Top 100 Auto Parts Makers" report released by the Korea Automotive Technology Institute (KATECH) today (October 21), the combined revenue of the top 100 auto parts companies (based on Automotive News) in 2025 reached $939.6 billion, up 2.0% from the previous year.
With global production of passenger and light commercial vehicles increasing by 3.9% year-on-year, parts makers also posted moderate revenue growth.
Among them, the top 10 parts companies, which accounted for 39.8% of total revenue, drove revenue growth by taking up 71.6% of the total revenue increase.
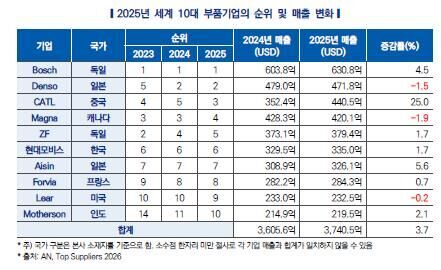
Germany's Bosch defended its top spot, posting a 4.5% increase in revenue compared to the previous year.
Germany's ZF, which ranked 2nd in 2023, fell to 5th last year. Given business restructuring efforts such as pursuing the sale of its Advanced Driver Assistance Systems (ADAS) business, a weak trend is expected to continue for the time being.
Germany's Continental, which ranked 9th in 2024, spun off its automotive business division excluding tires into Aumobio last year, resulting in Aumobio and Continental ranking 11th and 38th, respectively.
On the other hand, China's CATL saw its revenue surge by 25.0% year-on-year, rising from 5th place in 2024 to 3rd place last year.
The growth appears to have been positively influenced by rising battery demand, driven by a 29.0% increase in new energy vehicle production within China.
India's Motherson, which ranked 11th in 2024, entered the top 10 for the first time last year, backed by moderate revenue growth and the impact of the Continental-Aumobio spinoff.
Hyundai Mobis, the only South Korean company to make the top 10, maintained its 6th place ranking following the previous year.
Based on revenue growth rates, 9 out of the top 10 companies—including the U.S.'s Qualcomm (36.0%) and China's Gotion (32.7%), FinDreams (30.0%), and CATL (25.0%)—were related to electrification and intelligence sectors.
In particular, 7 of the top 10 were Chinese companies.
By region, Asia accounted for the highest share of the top 100 parts makers' combined revenue at 39.4%, followed by Europe at 29.0% and North America at 27.3%.
China's Gotion and Desay SV, which both rely on Asia for over 90% of their revenue, achieved double-digit revenue growth.
Looking at the top 100 parts makers by country, Japan had the most companies at 23, the same as the previous year.
The U.S. (17 to 16), Germany (16 to 15), and South Korea (10 to 9) each decreased by one.
In contrast, China increased from 14 companies in 2024 to 16 in 2025.
Last year's revenue for the 9 South Korean companies rose 2.3% year-on-year to $74.77 billion, accounting for 8.0% of the total.
Revenues increased for 6 out of the 9 companies, with relatively positive results observed among those that achieved regional revenue diversification.
The report forecasted, "The parts industry will be influenced by industrial paradigm shifts such as electrification and intelligence, as well as changes in the global trade environment," adding, "In particular, companies with supply records for Chinese finished car manufacturers are likely to secure additional supply opportunities as Chinese automakers expand their overseas localization."
(Photo provided by the Korea Automotive Technology Institute, Yonhap News)
※ Please note: This article was translated by AI and may contain errors.
Copyright Ⓒ SBS. All rights reserved. Unauthorized reproduction, redistribution, and use for AI training are prohibited.